
Small Business • Advertorial
Small Business > Exclusive Funding Spotlight
My Business Was Growing.
I Took Fast Cash to Cover
Payroll and It Nearly
Crippled Me. Then
I Found $77,000 at 0%.
 89.5K
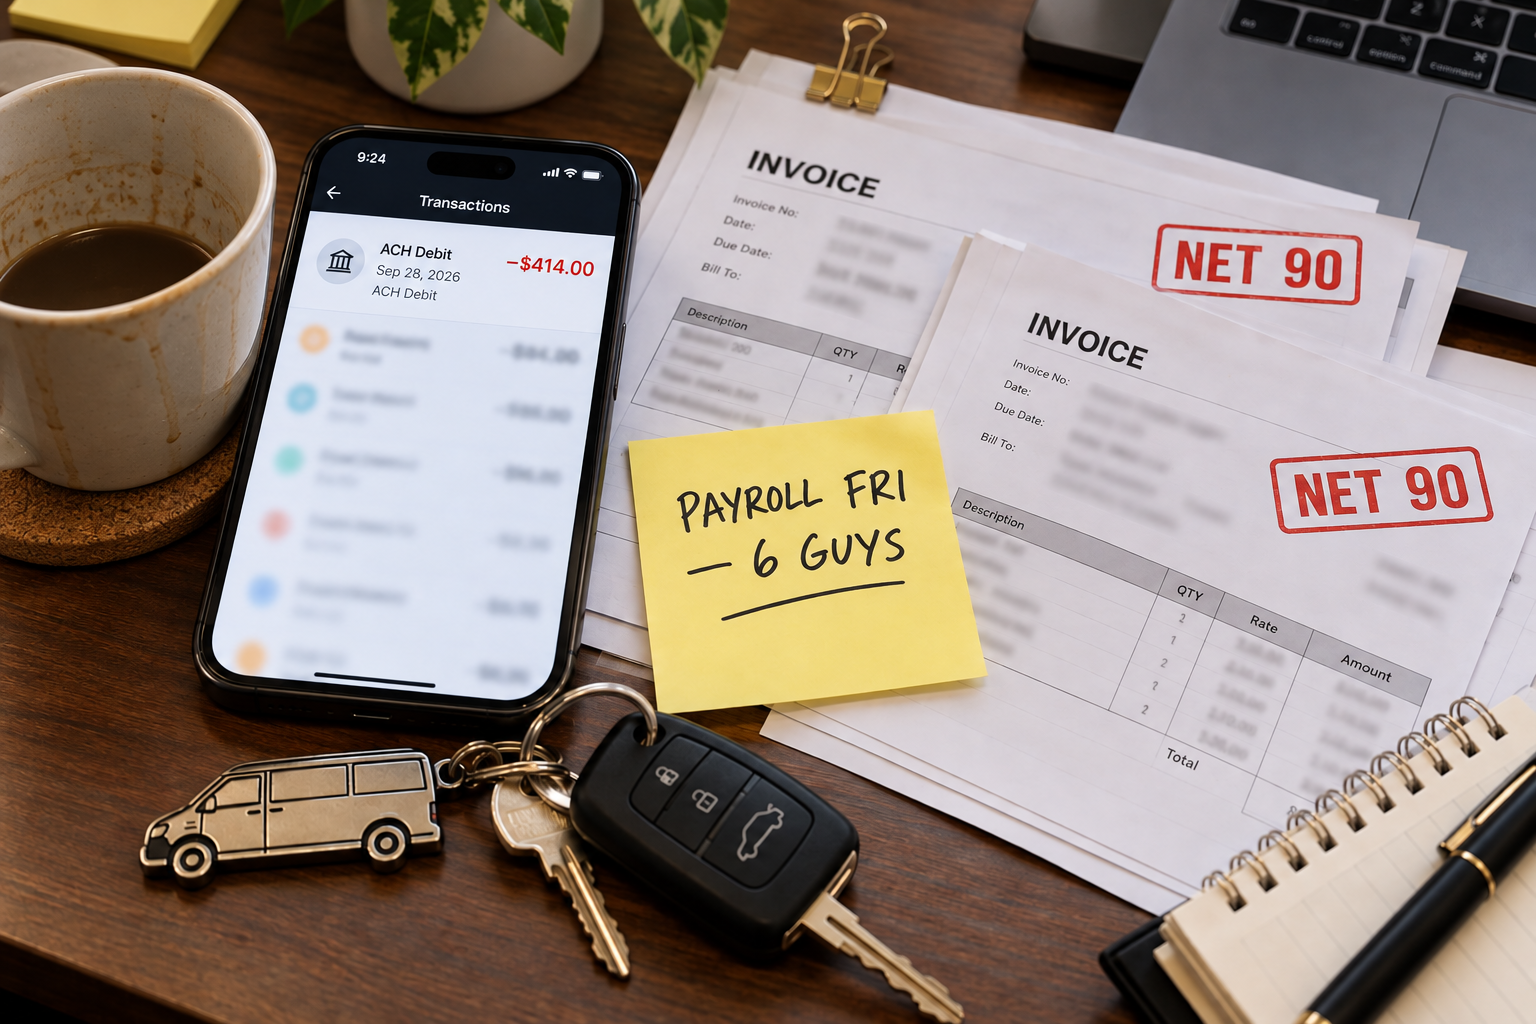
Nick Reed started with one van and a secondhand pressure washer. Eight years later, he runs three crews.
An $18,000 “fast business loan” started pulling $414 from his checking account every weekday. A different funding strategy later helped him secure $77,000 in business credit at 0% for 12 months, without tax returns, collateral or proof of income.
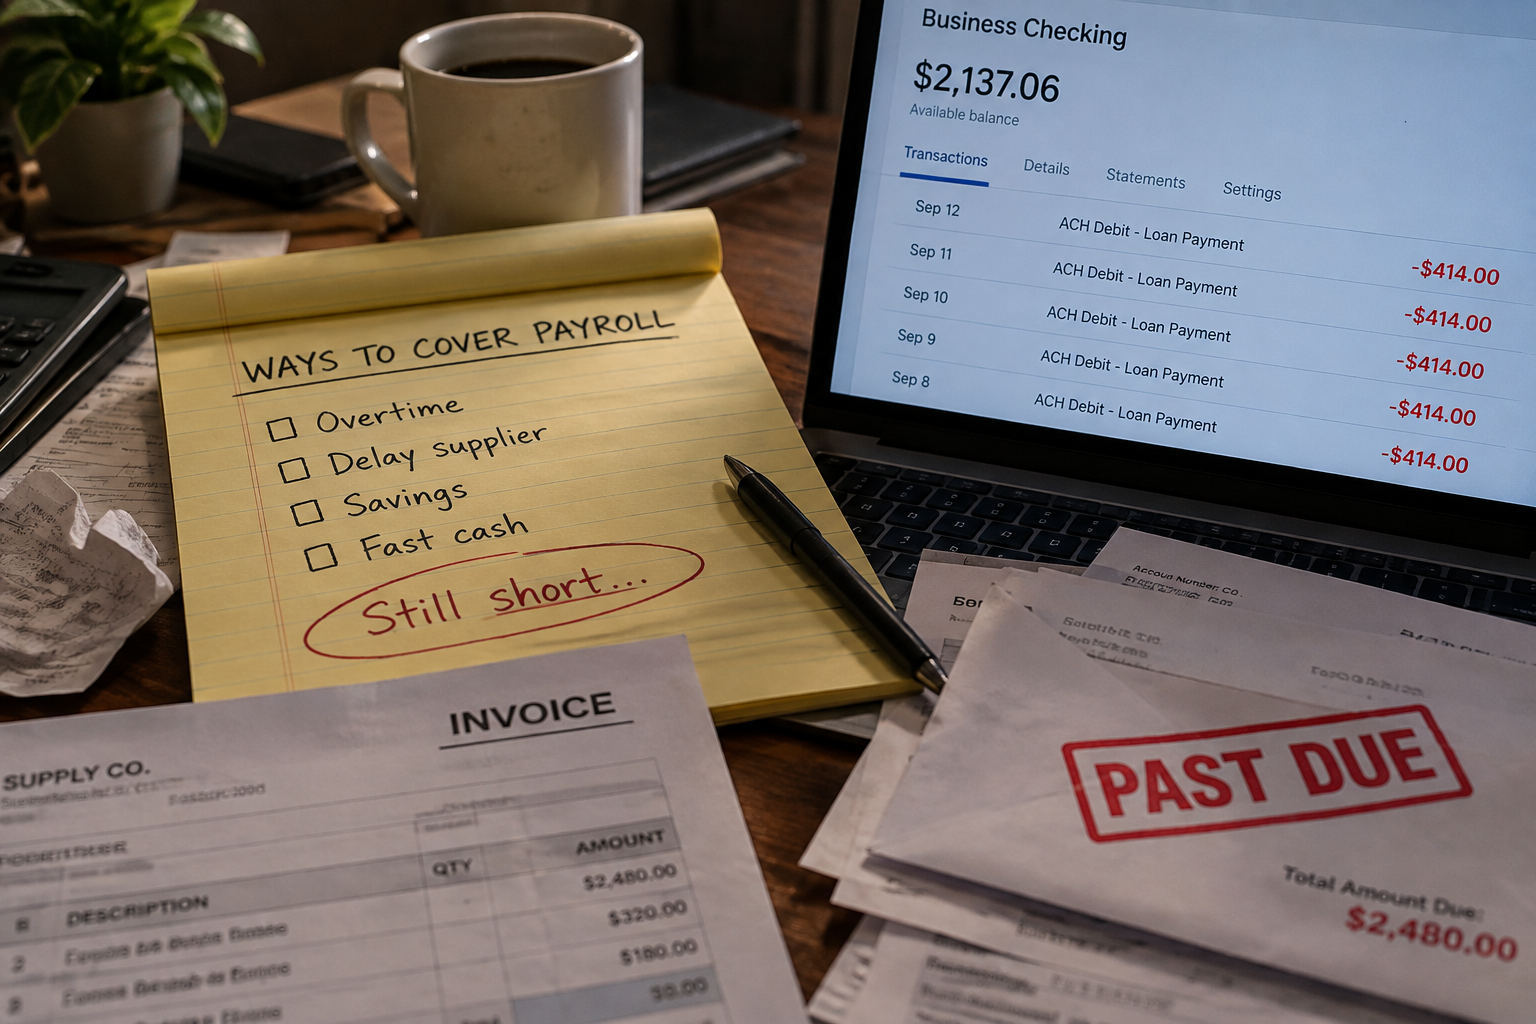
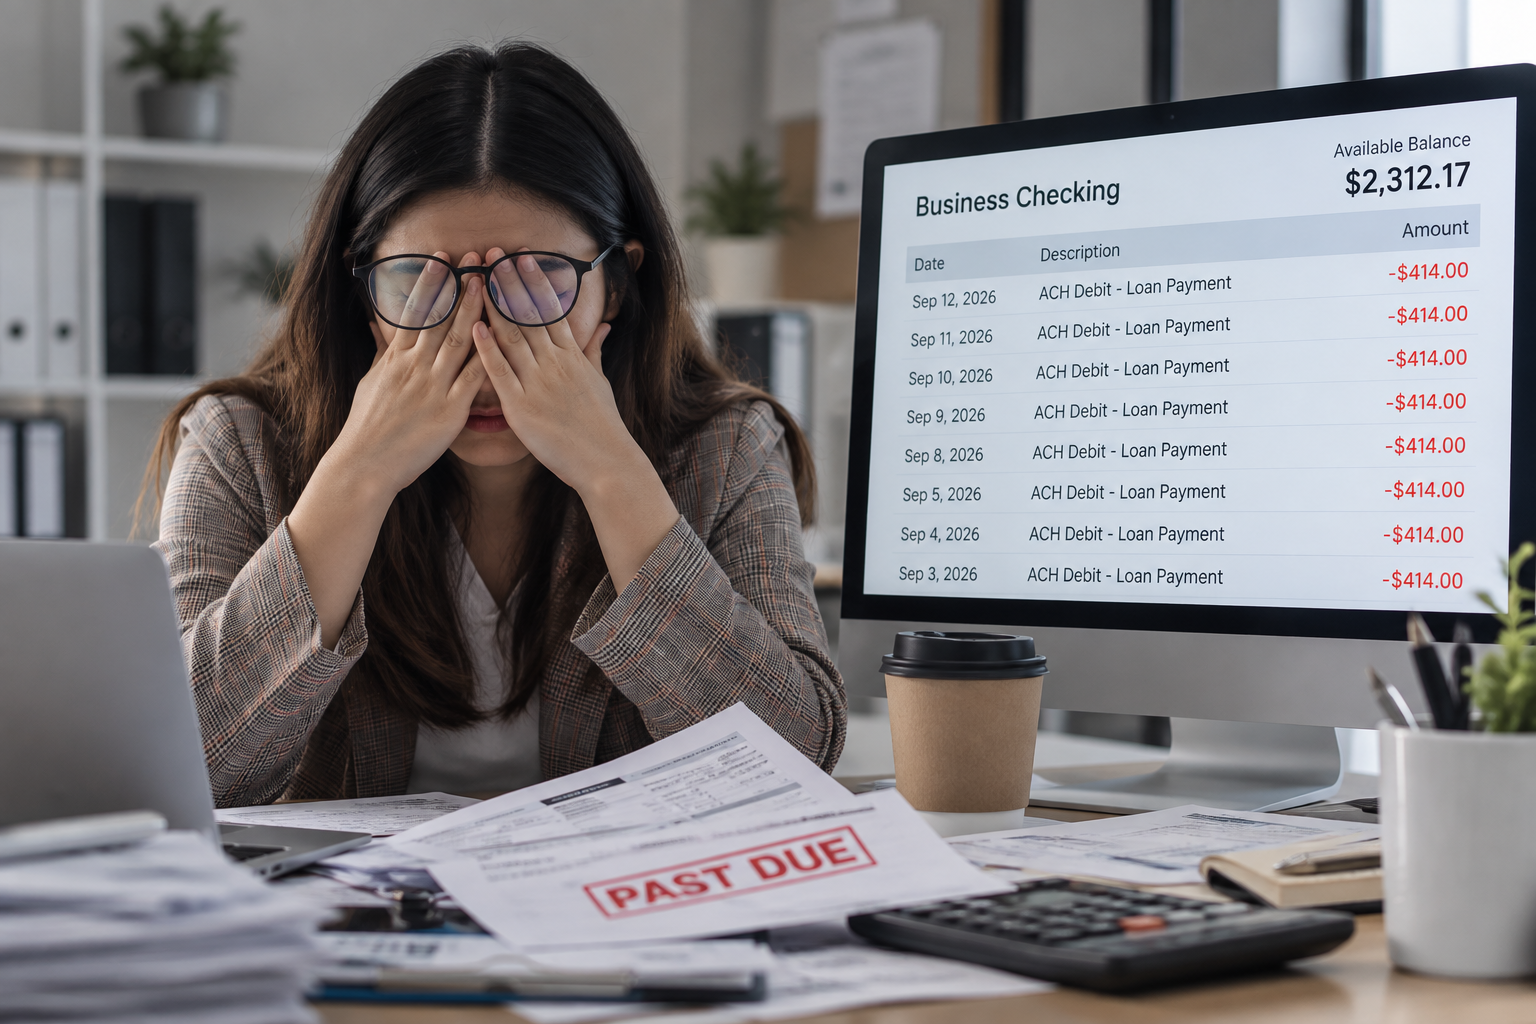
At 6:43 on a Friday morning, Nick Reed opened his business checking account and watched $414 disappear. By that afternoon, 6 employees expected to be paid, but two customer invoices still hadn’t cleared.
It was the fifth withdrawal that week. Nearly $9,000 had been pulled from the account over the previous month, whether Nick’s customers had paid him or not.
Nick had started the company eight years earlier with one van and a secondhand pressure washer. Now he had three crews, a full calendar and more work than his team could comfortably handle.
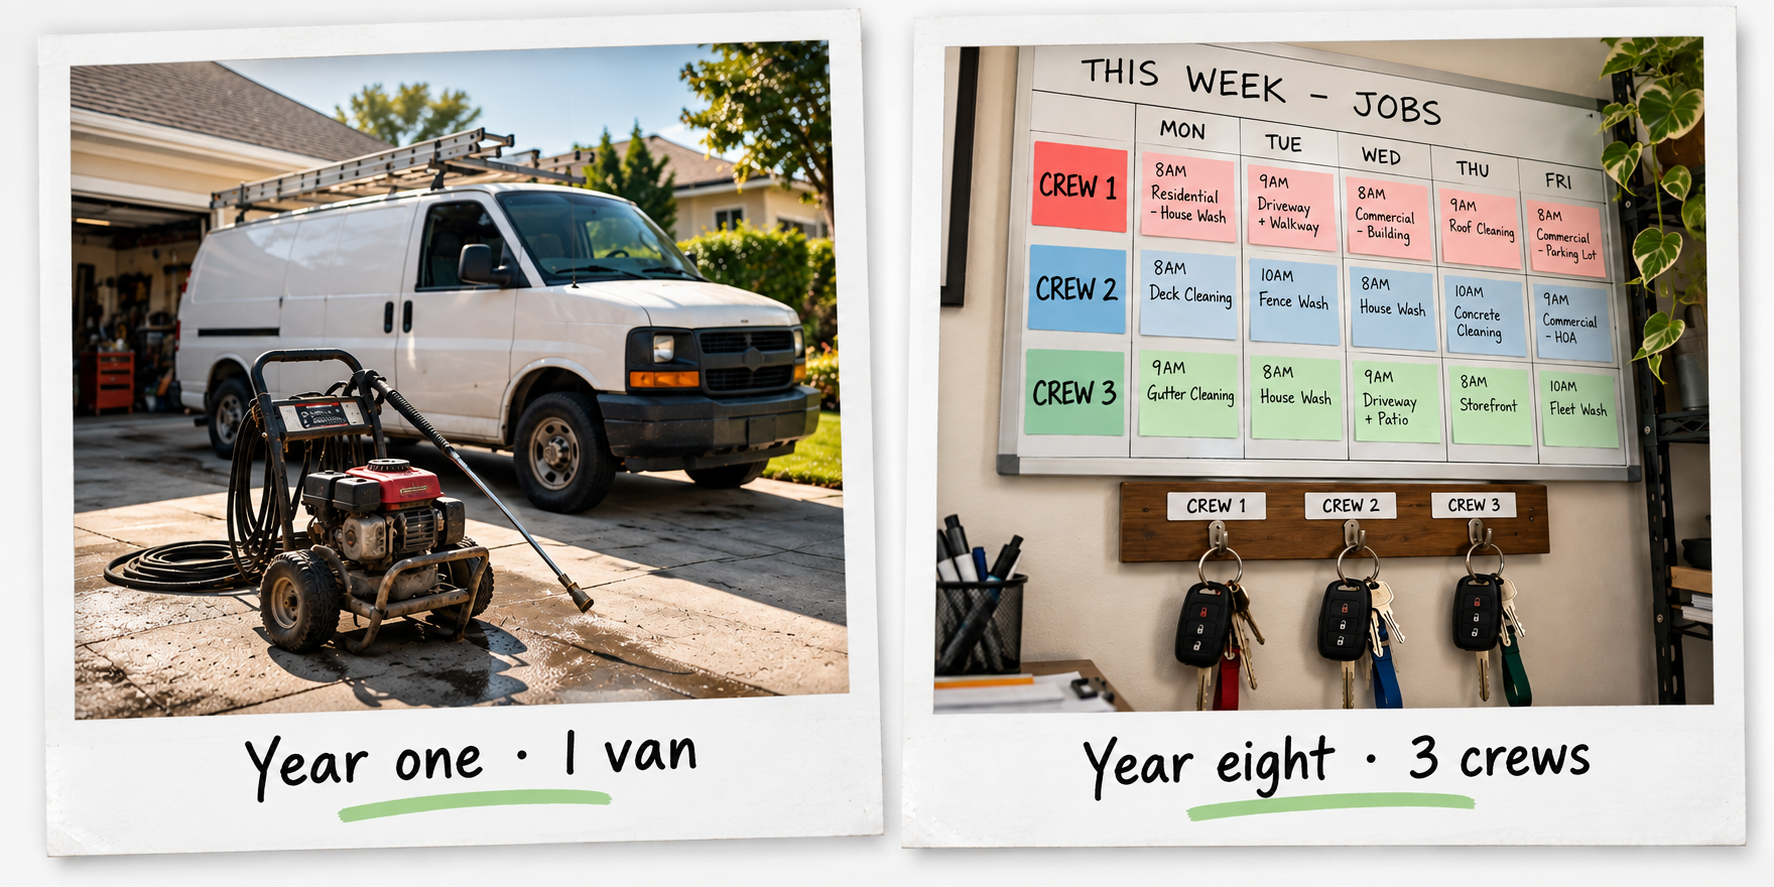
The business wasn’t in distress. Earlier that summer, growth had forced Nick to hire ahead of revenue. A property-management contract added dozens of locations, but its invoices paid on net-90 terms. Labor, fuel and supplies had to be covered.
Exhausted after a long workday, with payroll approaching, two customer invoices still unpaid, and another supplier bill due, Nick saw an online ad offering a “fast business loan” and filled out the form.
His cell phone rang before he closed the browser.
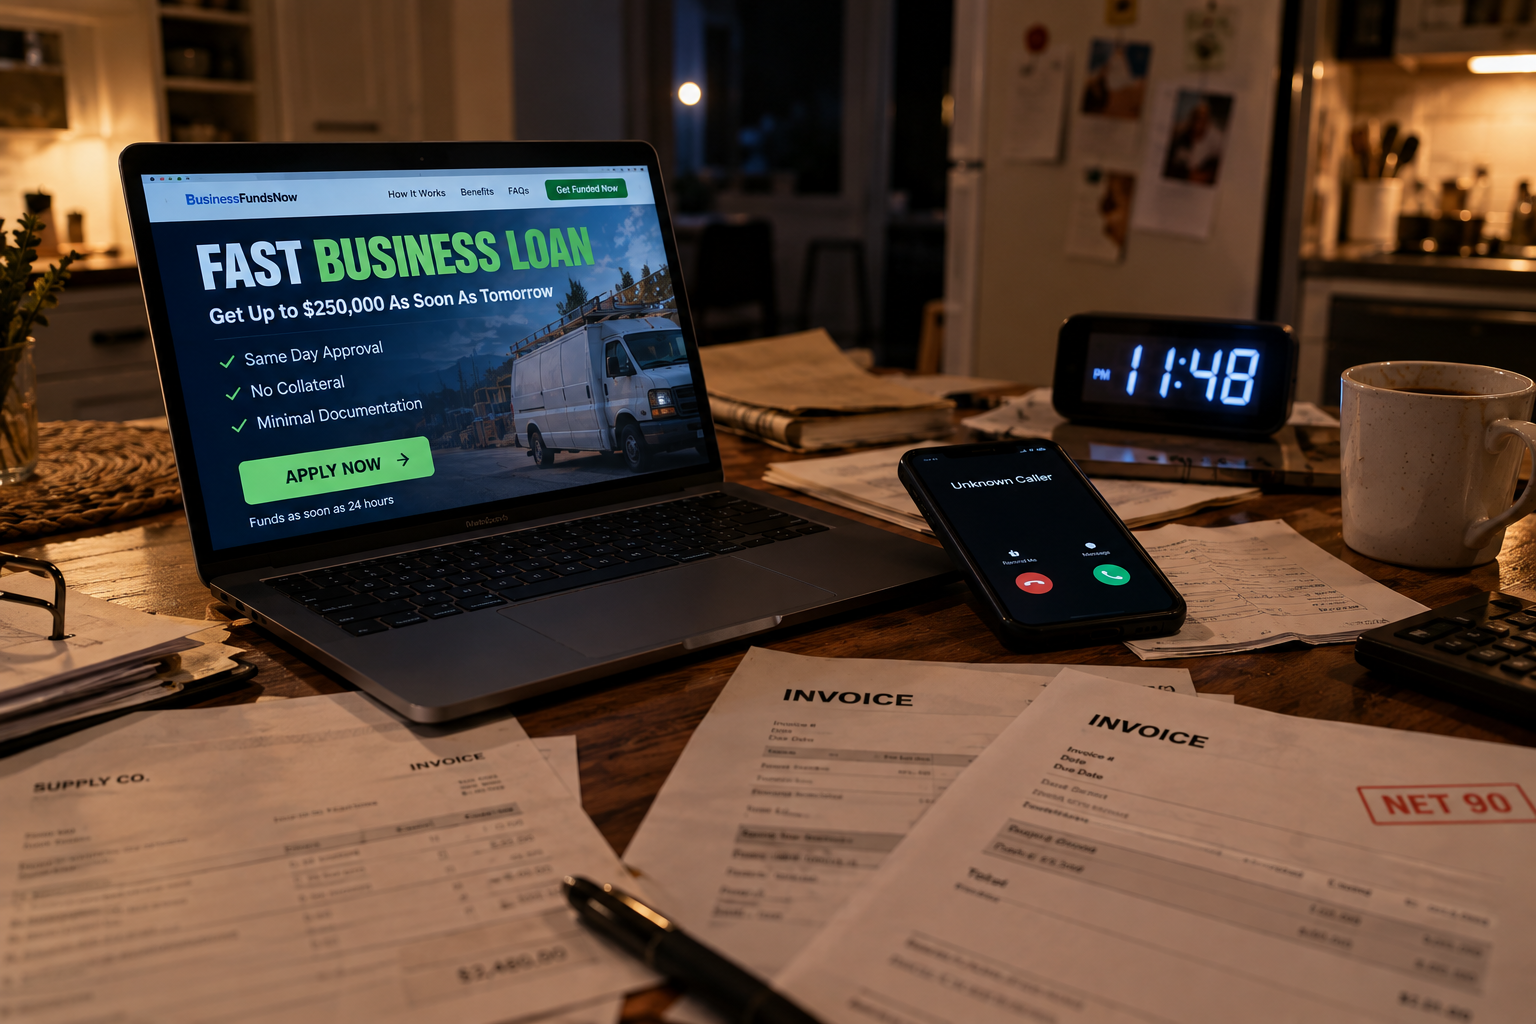
The approval came the same afternoon. The next day, $18,000 landed in the account.
The representative focused on two things: the company’s monthly deposits and how fast they needed money. The approval came that afternoon. The next day, $18,000 landed in the business account.
Nick thought he had bought time.
What he didn’t realize was he’d bought a new deadline.
The money solved Friday’s payroll. By Monday, the payments had created an entirely different problem.
The cash advance was repaid through automatic daily debits. They continued whether or not the company collected an invoice, lost a workday to rain or had to replace a broken piece of equipment.
Nick knew the total amount he’d have to repay. What he didn’t realize, and what countless business owners discover too late, was what those automatic daily payments would do to his cash flow.
“I stopped looking at the monthly numbers,” he said. “I was looking at tomorrow morning. Could everything clear?”
How Much 0% Business
Credit Could You Qualify For?
Answer a few quick questions to see whether your credit profile may support $50,000–$100,000+ in introductory 0% APR business credit.
The hidden cost of paying for speed
Products sold as fast business loans are attractive for an obvious reason: speed.
Funding can sometimes arrive in a day. For an owner staring at payroll, inventory or an emergency repair, speed can drive their decision. But fast-funding products don’t always use a conventional interest rate.
Instead, they charge a fixed factor rate and collect repayment daily or weekly.
NerdWallet’s analysis of this type of financing notes that effective APRs can range from 40% to 350%, depending on the fee, repayment speed and revenue. Fixed withdrawals continue regardless of how much the business earns during a particular period.
Speed can have value when an owner has exhausted less expensive options and has enough dependable cash flow to absorb the payments. But the structure can be punishing when the original problem is uneven cash flow.
The breaking point came when a customer pushed a $22,000 payment into the following week. Nick moved personal savings into the company’s checking to make payroll. Then he started looking for another type of capital.
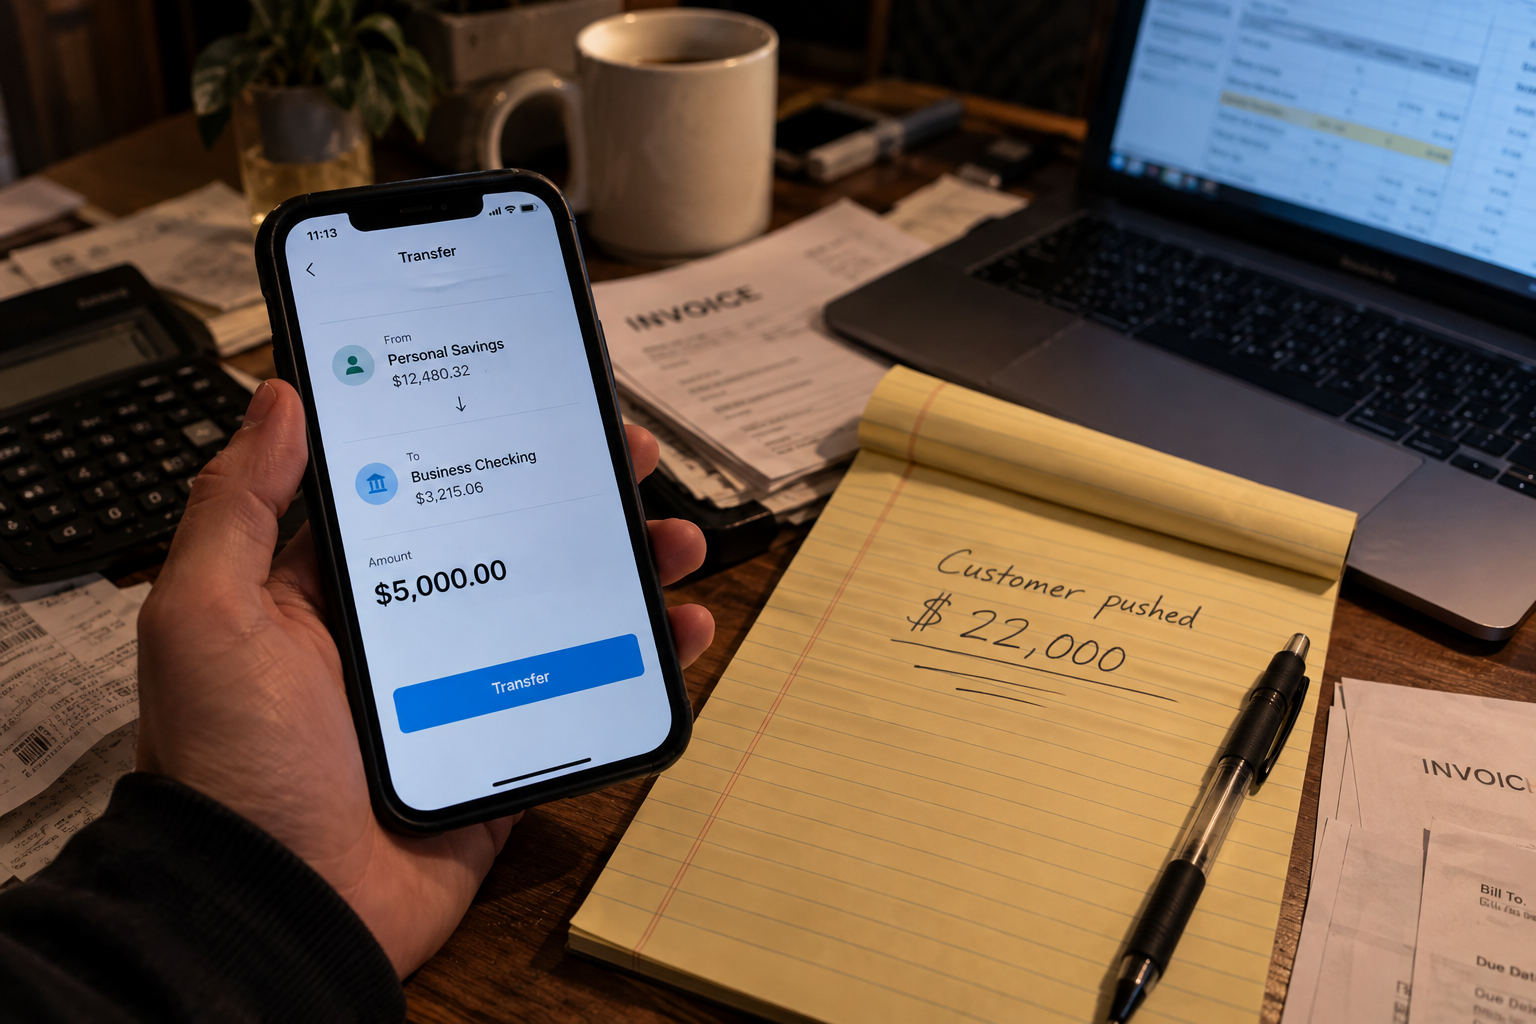
A delayed $22,000 invoice pushed Nick to cover payroll from personal savings.
The option his credit profile had been hiding
Nick assumed good credit made the process simple: choose a business card and apply. But a strong score was only the starting point. It couldn’t tell him which bank to approach first, which applications could be submitted together or how one approval might impact the rest.
Two business owners can walk in with similar scores and walk away with completely different limits. Before Nick applied, FundWithCredit reviewed the details behind his score and mapped the order in which he would apply.
The team looked at:
Rather than handing clients a generic list of cards, its team analyzes the owner’s full credit profile, banking relationships and application history before determining which institutions to approach and in what order.
The company describes the target as $50,000 to $100,000 or more. Owners with stronger profiles may exceed that.
FundWithCredit primarily works with U.S. business owners whose personal credit is around 740 or higher and who intend to use revolving business credit deliberately rather than as permanent debt. Available limits depend on the full applicant profile and each issuer’s decision.
How the FundWithCredit process works
Nick began with a 60-second quiz.
That included a soft inquiry, which didn’t impact his credit score. That allowed FundWithCredit to evaluate whether his profile appeared suitable before asking him to submit credit applications.
After reviewing Nick’s personal credit and business information, the team built an application sequence around his profile.
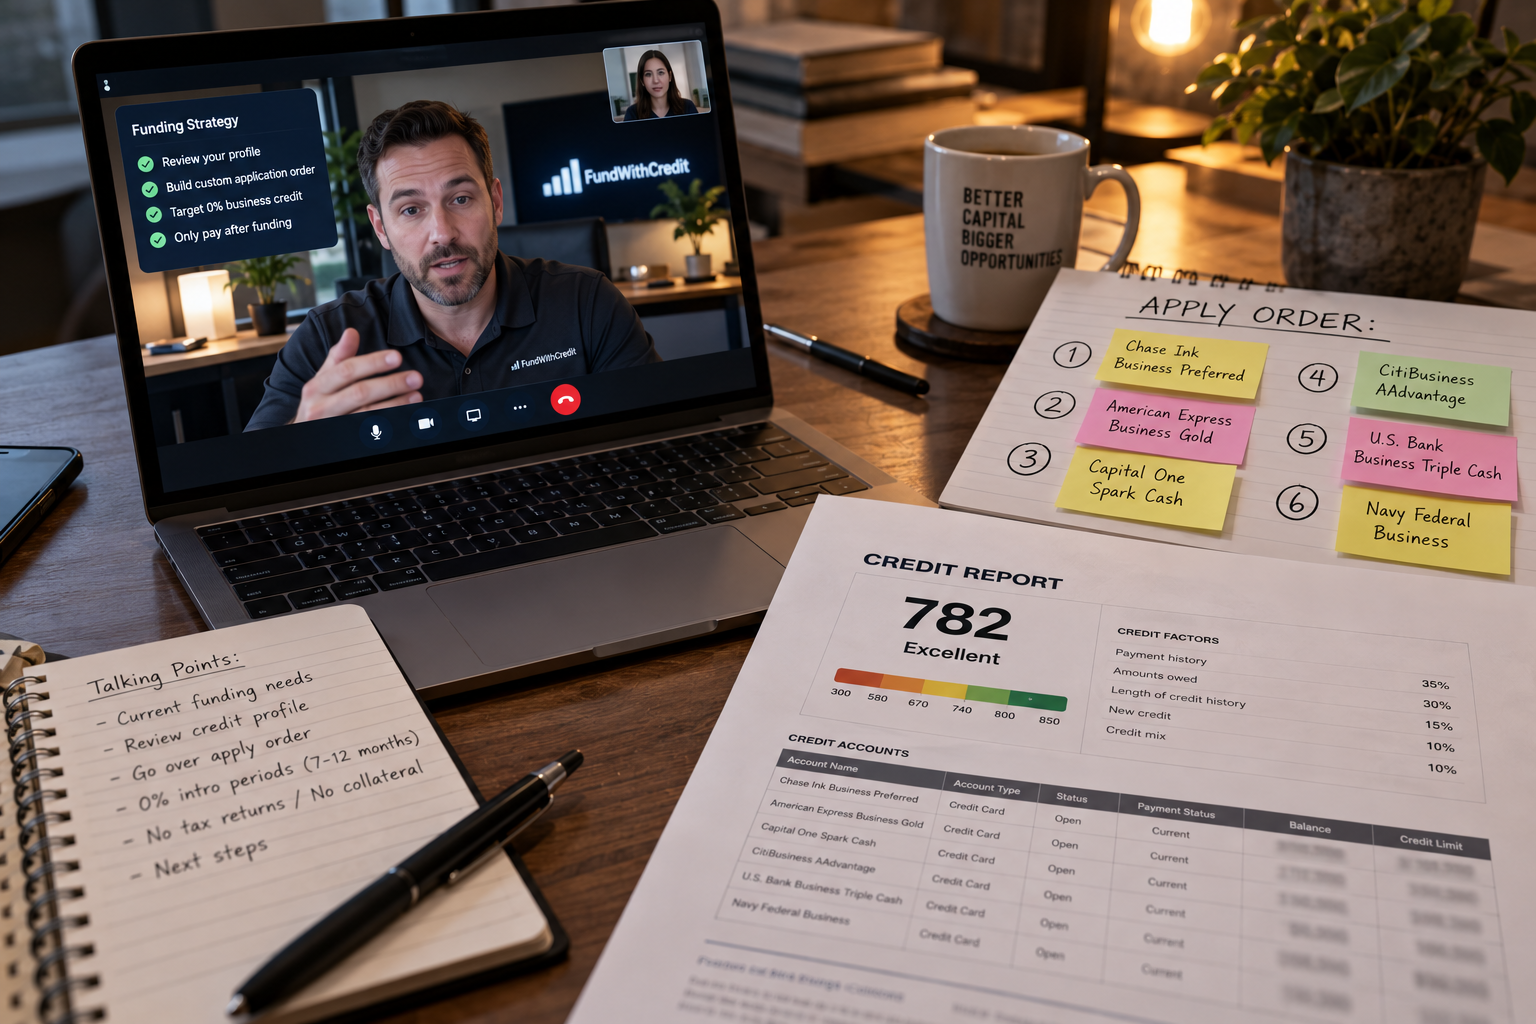
A U.S.-based funding specialist mapped which issuers to approach, and in what order.
The company’s service included:
Beyond the access to 0% capital, Nick valued the hands-off process most. He could stay focused on running the business while the team determined which institutions to approach, how to sequence the applications and how to maximize terms.
$0 upfront. Only paid on performance.
There was another difference Nick noticed immediately: FundWithCredit didn’t ask him to risk thousands of dollars in consulting fees before knowing whether the strategy would work.
Clients still have to repay what they borrow, along with any account or transaction fees charged by issuers. But FundWithCredit only gets paid after it secures funding for the client. If the company doesn’t produce a result, it doesn’t get paid.
Nick also worked with a U.S.-based funding specialist who’d gone through the FundWithCredit process as a client before joining the team.
The result: approvals totaling $77,000 in 13 days
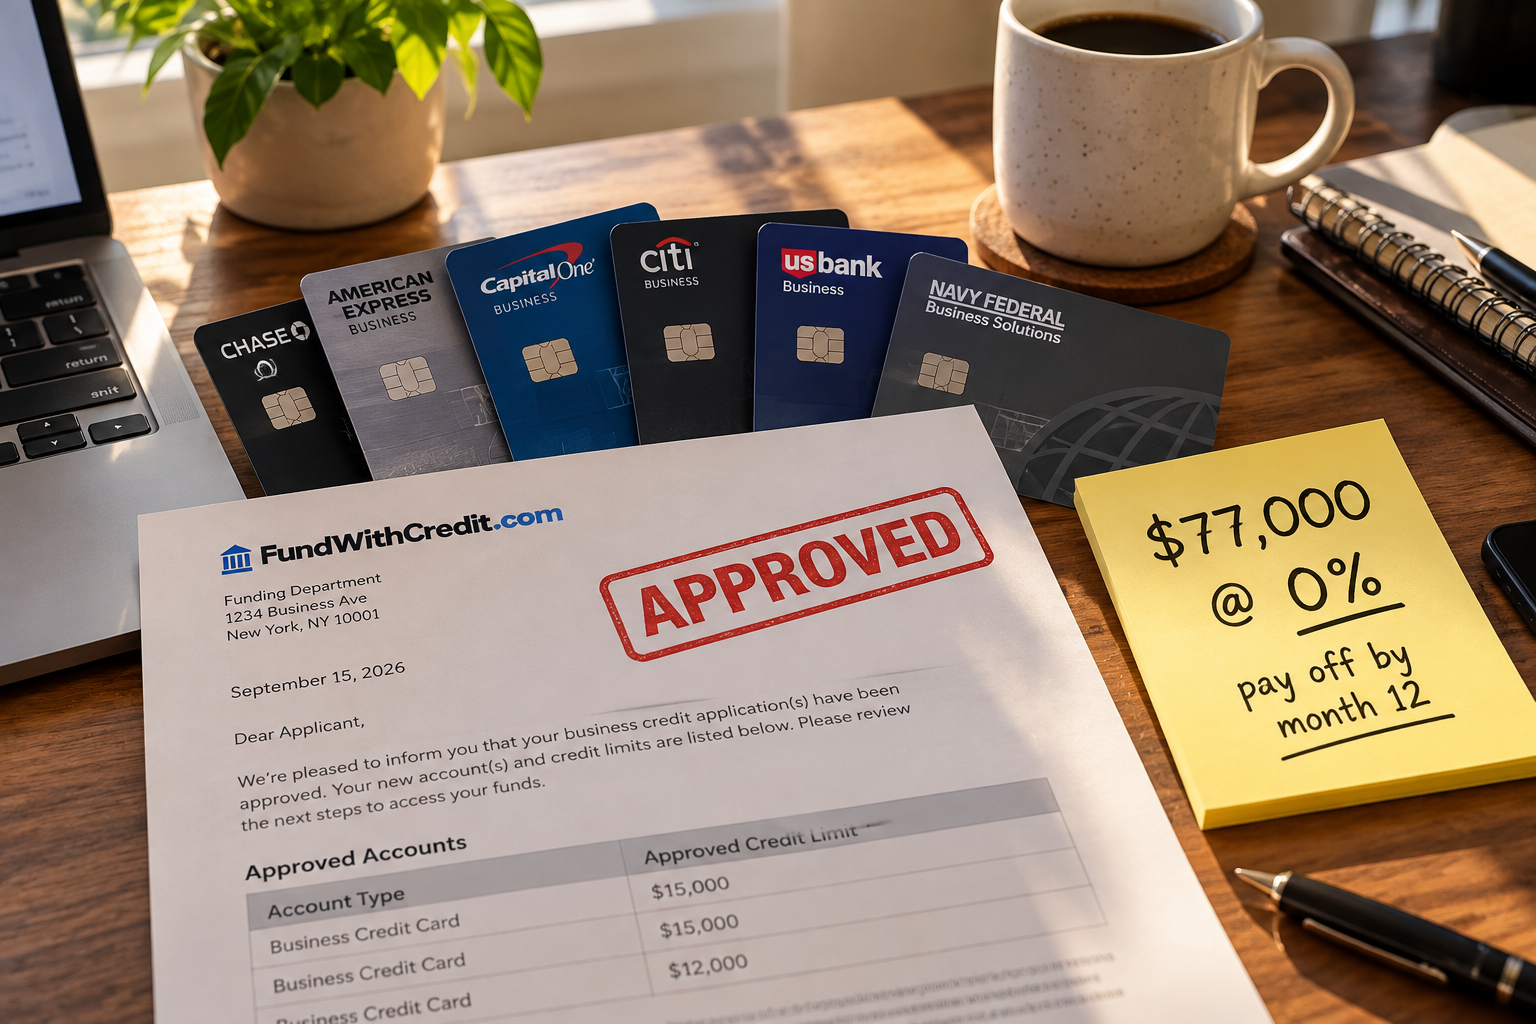
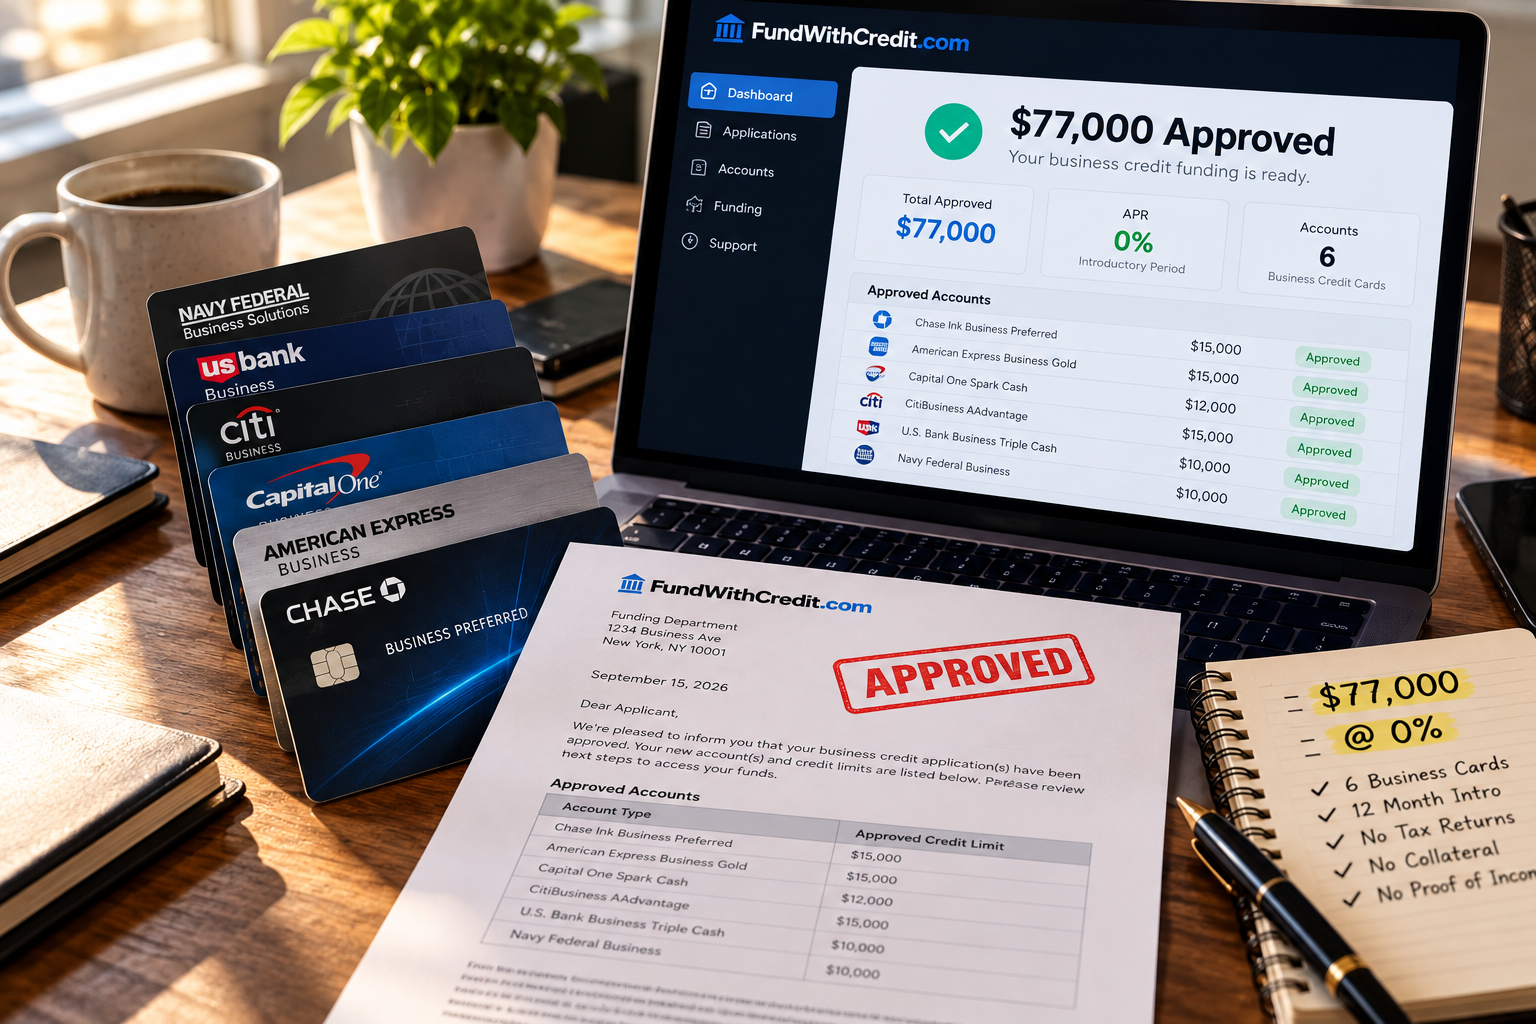
Over 13 business days, Nick received six business-credit approvals totaling $77,000.
The accounts offered introductory 0% APR. Across FundWithCredit’s current product universe, these periods generally range from 7 to 12 months, with the majority lasting 12 months.
Nick moved card-eligible expenses such as fuel, materials, software and advertising onto new accounts. That left more cash arriving from customers available for payroll and other expenses.
At the same time, eliminating the daily debit gave the operating account room to recover between receivables.
"
The $77,000 was huge. But the real change was focusing on business without a withdrawal hitting me every day.
— Nick Reed, business owner
Nick created a repayment plan tied to his company’s receivables and the expiration date of each introductory offer. He tracked the balances separately and planned to repay them before standard interest rates took effect.
How Much 0% Business
Credit Could You Qualify For?
Answer a few quick questions to see whether your credit profile may support $50,000–$100,000+ in introductory 0% APR business credit.
Before taking fast money, ask a different first question
Nick had not made a reckless decision when he accepted the $18,000. He made a rushed decision with incomplete information and a payroll deadline approaching. Only later did he understand what that speed would cost his business.
For owners with strong personal credit, the first question should not be: “Who can put money into my account tomorrow?” It should be:
How much 0% business credit can I access, and which application comes first to maximize my total approval?
FundWithCredit offers a simple quiz for U.S. business owners who want to explore that question. The initial eligibility review uses a soft inquiry and doesn’t impact the owner’s credit score. If the profile appears eligible, the company explains the potential range, process, fees and next steps before the owner decides whether to proceed.
See how much 0% business credit your profile may qualify for before accepting fast money.
Checking initial eligibility uses a soft inquiry and does not affect your credit score. Subsequent applications for credit generally involve hard inquiries. FundWithCredit is not a lender. All approvals, limits, promotional periods and terms are determined by issuing institutions. Introductory 0% APR periods generally range from seven to 12 months, with the majority lasting 12 months; standard account terms apply afterward. FundWithCredit charges a success fee for consulting services. Individual results vary. Images are illustrative. This content is advertising and is not financial, legal or tax advice.
Get 0% Business Credit
Without The Daily Debits

Owners are ditching
daily debits.
Watch their stories and see real client results.
A custom application sequence replaced his $414 daily debit with $77,000 at 0%.

Smarter capital for small business